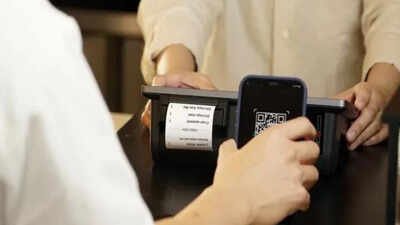
SBI chairman CS Setty sees UPI as an opportunity to provide credit lines through Kisan Credit Card, mudra loan, overdraft against mutual funds. He sees UPI with the potential to become a point-of-sale credit platform, with credit made available when customers transact through UPI and vows to work with NPCI and other lenders to ensure that MDR is not passed on to consumers. Excerpts:How do you see the impact of MDR?An estimated 96% of transactions will not attract MDR, as person-to-person transactions and person-to-merchant transactions of up to Rs 2,000 are exempt and there are several other carve-outs. We are developing technology to identify these transactions, and it will be ready by Oct 15, when MDR kicks in.
How will banks ensure MDR costs are not passed on to customers?Banks and NPCI will ensure that MDR is not passed on to retail customers or small merchants through system-driven MDR calculation, merchant classification and transaction-level pricing controls. Awareness campaigns by banks, IBA and NPCI, along with grievance-redressal mechanisms, will further strengthen transparency.Does MDR give SBI ammunition to regain UPI market share?MDR should be viewed in the context of sustaining investment in technology, fraud-risk management and capacity building. Two years ago, our UPI volume was below 10 crore transactions a day. Today, we handle around 20 crore transactions daily, representing around 25% of the total ecosystem size. Volumes of this scale, which is also increasing exponentially, require continuous investment in technology. We operate the largest proactive risk-management department, which monitors every transaction while building capacity for future growth. MDR should therefore be viewed from this perspective, rather than merely as a revenue item. It would help us invest further in tech and risk management and serve customers better.Will MDR allow you to offer incentives for using Yono for UPI?The improvements are not contingent on MDR. We had been investing in the app even before discussions on MDR began. Yono is a comprehensive service application, and we have simplified the payments experience to increase convenience and daily engagement.Do you see increased use of SBI’s Yono app for UPI?We have revamped UPI on Yono 2.0 and aim to drive greater usage among our customers, including new-to-bank customers. We have 10 crore registrations, of which five crore are active banking users. However, many customers use third-party apps as well. We have simplified the UPI experience on Yono, which currently handles 1-2 lakh transactions a day. Our objective is to increase this to five crore transactions a day over the next two years and position Yono among the top five UPI apps. SBI is already the largest remitter bank on UPI, and we also want Yono to become one of the most preferred apps.What is SBI’s plan for the UPI business?Our ambition is to build a large-scale, sustainable and customer-centric UPI franchise across the value chain. We aim to consolidate our strong issuer and remitter position, and scale merchant acquiring beyond our existing 60 lakh merchants and approximately 13 crore monthly transactions. We will pursue this across offline merchants, including through UPI QR codes, as well as online merchants. We also plan to offer our customers a seamless, feature-rich and differentiated UPI experience, while deepening engagement with SBI’s broader digital services. Together, these will enable SBI to deepen customer engagement and expand its role in India’s digital-payments ecosystem.What is your assessment of the economy up to Sept?The broader economic momentum remains resilient, with sustained consumption demand supporting credit growth. Retail personal and MSME credit growth has been healthy, while corporate credit has also grown reasonably well, albeit with some moderation. GST collections further reinforce the resilience of the consumption story.Is the West Asia conflict affecting capex?Despite the West Asia conflict and the broader geopolitical environment, we have not seen any adverse impact on the capex momentum. Investment activity remains resilient, with project announcements, particularly in sectors such as power, translating into projects, implementation and subsequently the drawdown of credit lines. Even during periods of heightened geopolitical tensions, capex activity has continued, reflecting the underlying strength and resilience of the investment cycle.